Florida’s residential insurance crisis has drawn most of the headlines, but small business owners across the state are facing a parallel, less-discussed squeeze: commercial property and liability premiums that have climbed sharply over the past several years, cutting directly into already-thin margins.
A market shaped by the same pressures as homeowners insurance
Commercial insurers in Florida operate in the same reinsurance market as residential carriers, which means the same forces pushing up homeowners’ premiums — hurricane exposure, litigation costs, and reduced reinsurance capacity — apply to business policies as well. For a restaurant, a strip-mall retailer, or a small manufacturer, this has translated into premium increases that in some cases have outpaced revenue growth.
Which businesses are hit hardest
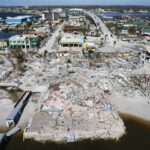
Businesses with older buildings, coastal locations, or properties with older roofs face the steepest increases, mirroring the underwriting standards now common in residential policies. Businesses that rely on outdoor operations — nurseries, marinas, outdoor event venues — often face additional scrutiny and higher rates due to their storm exposure.
How owners are responding
Some small business owners are raising deductibles to lower premiums, accepting more out-of-pocket risk in exchange for manageable monthly costs. Others are forming or joining regional business associations that negotiate group insurance rates, a strategy more common among larger franchises that is slowly spreading to independent operators. A smaller number have relocated inland or invested in hardening their properties — impact windows, reinforced roofing — to qualify for mitigation discounts.
The broader economic ripple effect
Rising commercial insurance costs don’t stay contained to a single line item. Business owners often pass a portion of these costs on to customers through higher prices, while others delay hiring or equipment upgrades to absorb the expense internally. Economists tracking small business formation in Florida have noted that insurance costs are increasingly cited as a factor in decisions to close, relocate, or scale back expansion plans.
What might help going forward
State-level reforms aimed at the broader insurance market may eventually filter down to commercial rates, but the timeline for meaningful relief remains uncertain. In the meantime, business advocacy groups are pushing for commercial-specific mitigation credit programs, similar to those already available to homeowners, that would reward businesses for hardening their properties against storm damage.