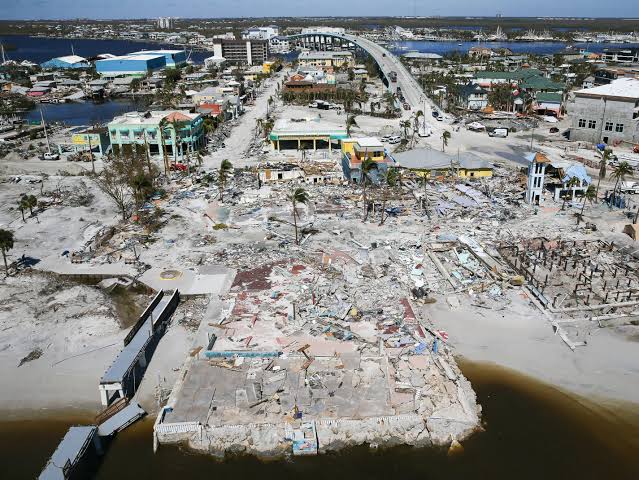
For most of the past five years, Florida’s property insurance market has been defined by one word: instability. Dozens of insurers have exited the state, gone insolvent, or stopped writing new policies altogether, leaving homeowners to absorb some of the highest premiums in the country. As 2026 continues, the market is showing signs of change — but not the kind of relief many residents were hoping for.
Why Florida’s insurance market broke down
The roots of the crisis go back further than any single hurricane season. A combination of rising reinsurance costs, a wave of litigation around claims disputes, and repeated direct hits from major storms pushed many insurers into the red. State-backed Citizens Property Insurance Corporation, originally intended as a last resort, became the largest property insurer in Florida almost by default, absorbing policyholders that private insurers no longer wanted.
What legislative reforms have actually changed
Florida lawmakers have passed several rounds of insurance reform aimed at reducing litigation costs and encouraging insurers back into the market. These changes include limits on attorney fee awards in insurance disputes and incentives for new or returning carriers. Insurance regulators have pointed to a small number of new companies entering the market as an early sign of stabilization, though few homeowners have yet seen meaningful decreases in their premiums.
What this means for homeowners right now
For most Florida homeowners, the practical impact of these reforms is still limited. Premiums remain elevated compared to pre-2020 levels, and coverage terms have tightened — higher deductibles for wind and hurricane damage, stricter roof-age requirements, and more frequent non-renewals for older homes. Homeowners in coastal and flood-prone areas continue to face the steepest costs and the fewest choices among carriers.
What to watch next
The 2026 hurricane season will be a key test of whether the market’s early stabilization holds. A significant storm season could quickly reverse recent gains, pushing more insurers toward exit or insolvency. Conversely, a quieter season could give the reformed market room to demonstrate whether the legislative changes are working as intended.
Florida homeowners concerned about their coverage should review their policy renewal terms carefully, confirm their insurer’s financial rating with the Florida Office of Insurance Regulation, and compare quotes annually rather than assuming their existing policy remains the best available option.